The Art of Investing | François Rochon | Talks at Google
Interview by Talks at Google
Talks at Google is a speaker series hosted at Google offices worldwide, featuring in-depth conversations with authors, entrepreneurs, investors, scientists, and thought leaders. The format combines a prepared talk with audience Q&A, offering an intimate look at how some of the sharpest minds in their fields think about their craft.
François Rochon, founder of Giverny Capital, lays out his complete investment philosophy — the art of going beyond the numbers to find rare, unique business masterpieces. He unpacks his three-pillar stock selection framework blending financial science, qualitative art, and management judgment, then illustrates it with detailed case studies of Disney and CarMax. The Q&A covers the Starbucks "one that got away," how to evaluate growing vs. shrinking moats, his four reasons to sell, and the famous "mistake medals" from his annual letters.
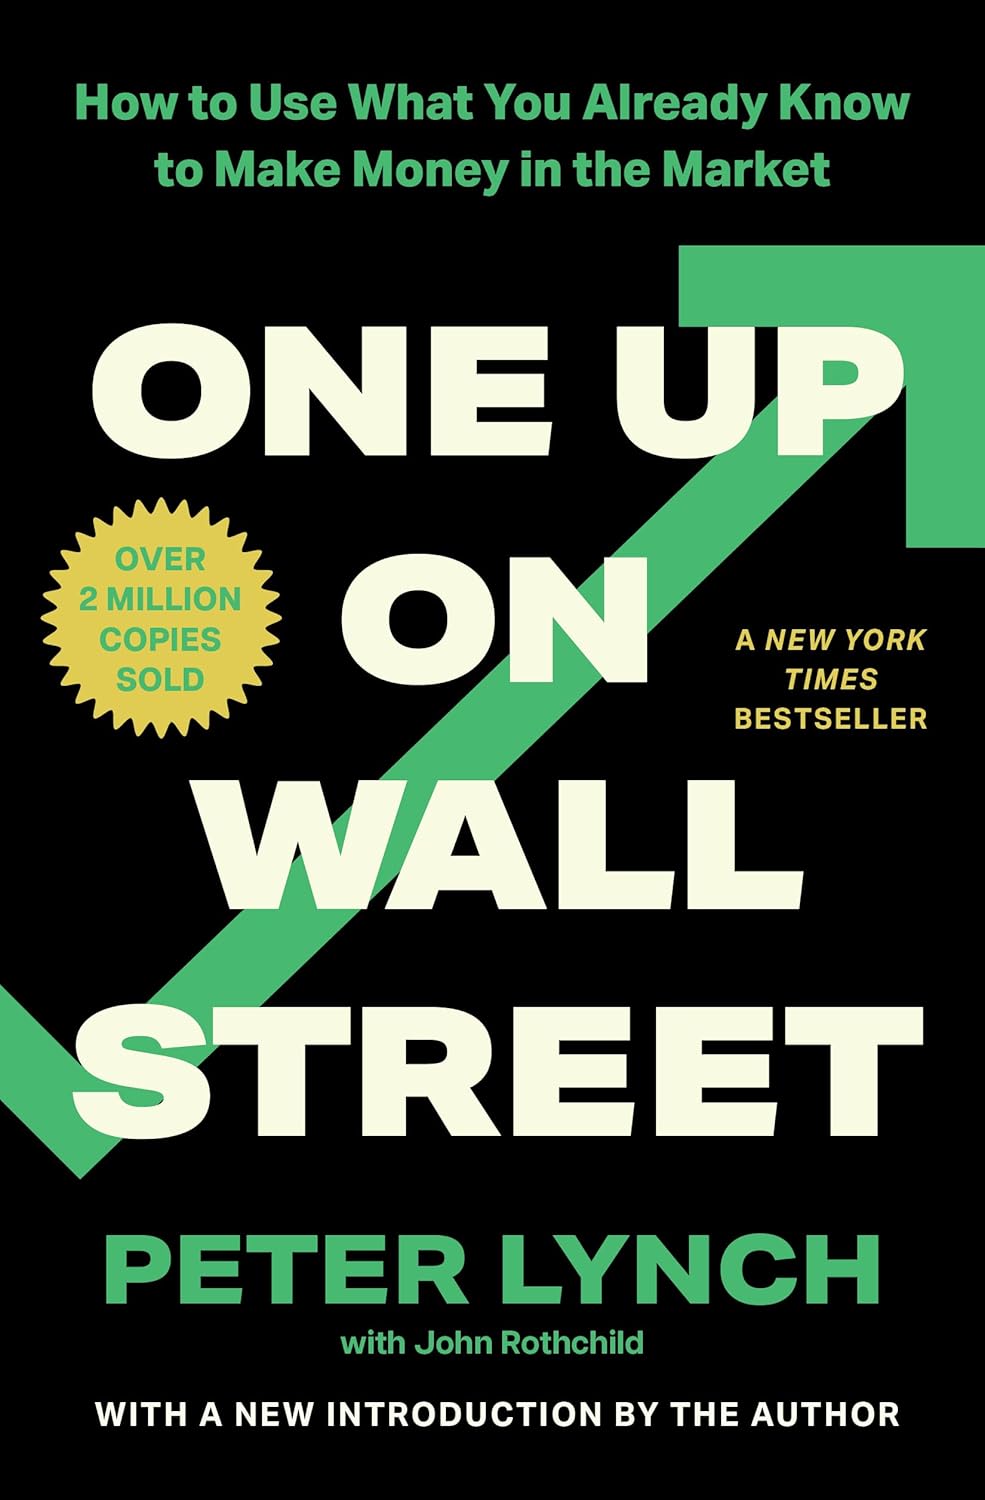
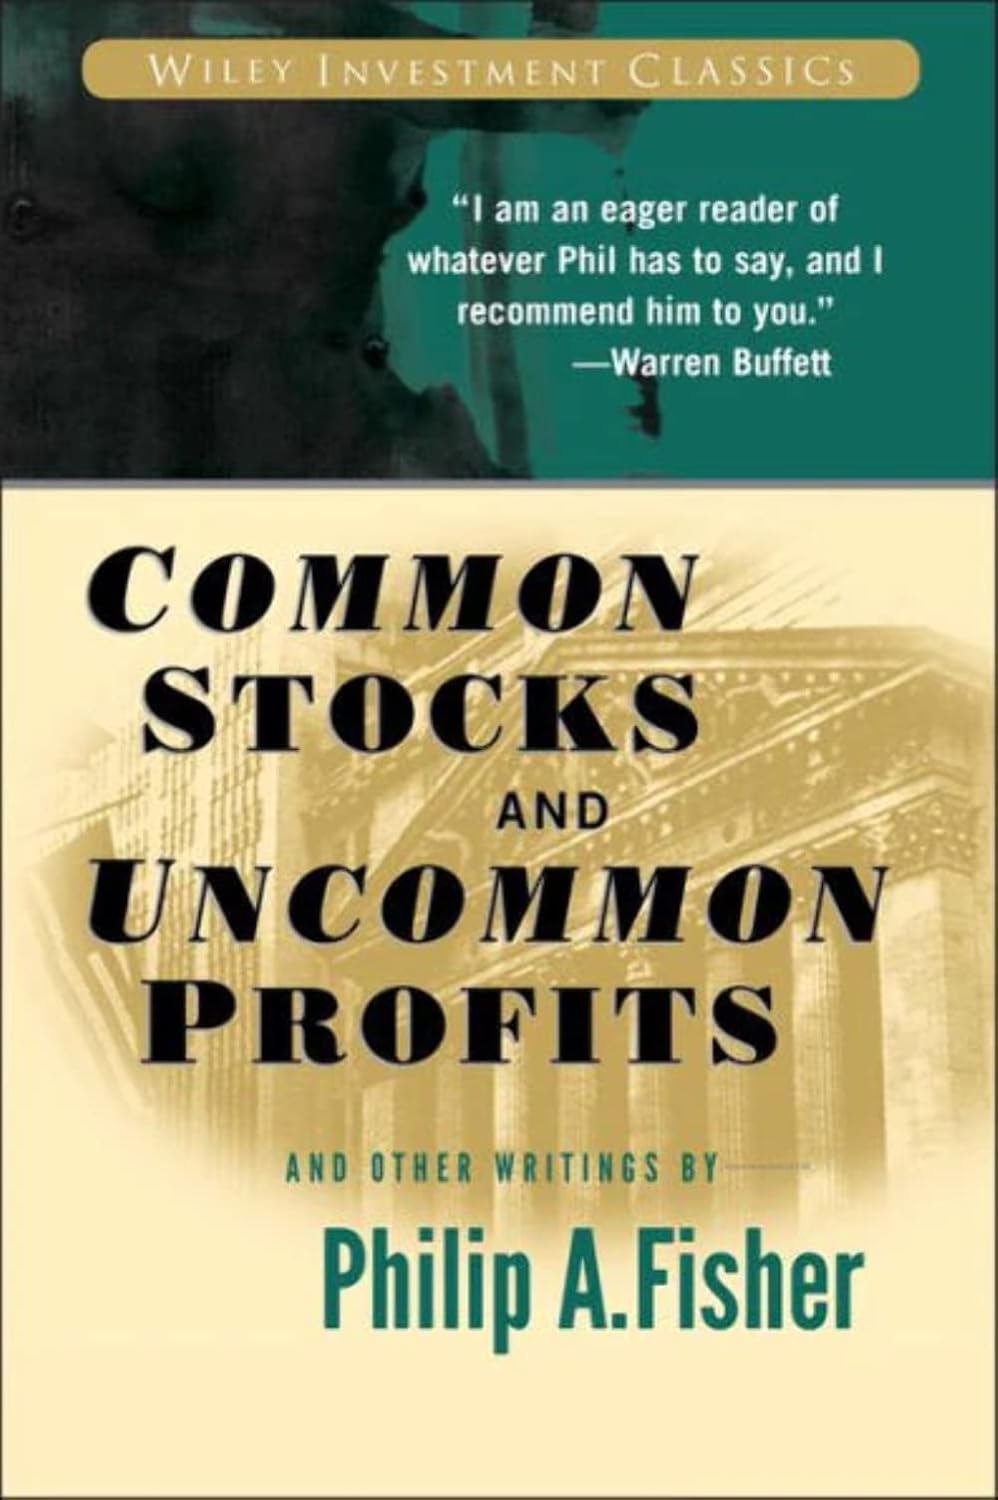
Books Mentioned
The Art of Going Beyond Numbers
Rochon introduces himself as an engineer with a passion for art who founded Giverny Capital. Peter Lynch's insight that "investing in stocks is an art more than science" shapes his entire approach. Scientific training brings advantages — comfort with numbers, avoiding financial dogma — but also disadvantages: looking only at past data, struggling with judgment calls, and needing to be precisely right when investing requires accepting you will be wrong 30–40% of the time and still succeed. He warns against lazy gut feelings masquerading as art: having a great feeling about a stock is not art, it is laziness.
Why Unconventional Thinking Beats the Index
To master investing as an art, Rochon says you must study the masters, practice actively, and develop your own style. Woody Allen: you learn jazz through love and osmosis, not forced study — the same applies to investing. Jim Collins: you can follow a paint-by-number kit or create your own masterpiece. Keynes warned that the long-term investor "will be eccentric, rash, and unconventional in the eyes of the average opinion." The data backs this up: the S&P 500 beats roughly 85% of professional managers, largely because of fees. To beat the index, you must think independently, own few selected companies, and cultivate rationality, humility, and patience. Trying to predict the market is a road to failure.
The Science and Art of Stock Selection
Rochon's stock selection framework has three pillars. Science: companies need high return on capital, growing earnings, strong balance sheets (debt-to-profit under 4×), market leadership, competitive advantage, and low cyclicality. Management must have high ownership — "in the same boat as we are" — with good capital allocation and long-term thinking. Valuation targets doubling your money in five years, or roughly 15% annually. Art: the best companies are rare, unique, and beautiful — what Rochon calls "masterpieces." He cites NCR, Apple, IKEA, Geico, McDonald's, Starbucks, and Google as business masterpieces from history. Their uniqueness is the equivalent of a moat with crocodiles and piranhas protecting a castle from competitors. Judgment: the subjective third pillar, epitomized by his test for management — "would I like this man to marry my daughter?"
Disney and CarMax — Two Case Studies in Patient Compounding
Disney: Mickey Mouse has three great qualities — he is globally popular, immortal, and has no agent. Disney's business model is like an oil field: create a hit movie, then re-release it 50 years later with no new capital investment required. Rochon bought at $24 in 2005 when Bob Iger became CEO. The stock went nowhere for four years while earnings kept growing — "we were patient." Over 12 years, earnings grew 13% annually and the stock more than quadrupled. CarMax: held for 10 years with 16% annual EPS growth. The P/E multiple compressed from 24× to 18×, yet the stock still delivered 13% annually — 5% above the S&P 500. Rochon added more shares at 14× earnings in 2011 and 2016. The lesson: when earnings compound, stock prices follow even if multiples contract.
The Investor's Competitive Edge
An investor's competitive advantage rests on three behaviors: patience, humility, and rationality. Humility means accepting that predicting macroeconomic events is impossible — "so we don't try to predict them." It also means knowing the limits of your circle of competence and recognizing mistakes when you make them. Rochon keeps his firm always invested, citing Woody Allen: "80% of success is showing up." Each year his annual letter awards bronze, silver, and gold medals to their best mistakes — a practice that is "very painful" but essential for continuous improvement. Rationality means resisting fads and being impervious to short-term market quotations, staying calm and focused on the long-term horizon.
The Rule of Three and True Patience
Rochon's Rule of Three: accept upfront that one year in three the market will decline 10% or more, one stock purchase in three will disappoint, and one year in three you will underperform the index. Even the best managers underperform one year in three — this is an ambitious target, not a conservative one. Internalizing these expectations prepares you psychologically for the rough patches. Patience is "not the ability to wait, but the ability to keep a good attitude while waiting" — which means focusing on company earnings, not stock price movements. But patience must be distinguished from stubbornness. Rochon uses the frog-in-boiling-water analogy: if fundamentals slowly deteriorate and you rationalize holding on, you get cooked. The art is knowing when patience crosses into denial.
The Unconventional Investor's Balancing Act
Rochon contrasts two investor types: the conventional investor focuses on market quotes, is short-term oriented, has an opinion on everything, and chases fads. The unconventional investor focuses on intrinsic value, has a long-term horizon, is agnostic about near-term market direction, and resists popular beliefs. But the real skill is balancing opposing forces: love for the craft without falling in love with stocks, broad knowledge while staying within your circle of competence, open-mindedness with independence of thought, patience without becoming a boiled frog, and discipline with the wisdom to know when to break your own rules. He closes with Templeton: "to obtain better results than the others, you have to do something different from the others." At Giverny, that means independent thinking, concentrated holdings, a 7-year average hold (versus Wall Street's 7 months), and the right behaviors.
Consistency Through the Tough Years
The host reads a 2005 interview where Rochon articulated the exact same philosophy — same words, same framework, 12 years earlier. Asked whether it has been easy to stay consistent, Rochon admits it has been deeply tested. Underperforming one year in three is painful when it happens, especially when you have to explain it to partners. It can last two or three years in a row. The only thing that carries you through is conviction that the principles are sound and will eventually work out. Patience, he says, is probably the single most important quality needed to succeed in the stock market.
Humility and Circle of Competence — Advice for New Investors
For those starting out, Rochon says the quality behind patience is humility: accepting you will make mistakes and that there is always more to learn. Warren Buffett's greatest quality is not intelligence — it is his humility. At 87 years old, he is still striving to learn every day. For individual investors, the practical advice is to stay within your circle of competence: there are thousands of companies, and trying to value all of them is playing a hard game. Being very selective and only pursuing businesses you truly understand is playing an easier game. Rochon invokes the Ted Williams analogy — waiting for the perfect pitch in your sweet spot. In investing, "there's no called strike" — you have the luxury of infinite patience. That is the most beautiful thing about this business.
Starbucks — The $100-Bagger That Got Away
Rochon first looked at Starbucks in 1994 and immediately recognized it as a unique business. Traveling in the US in the early '90s, he was struck by the bad coffee everywhere — in the greatest country in the world, this made no sense. Howard Schultz was an ambitious, driven CEO who was confident Starbucks could have thousands of locations globally. Rochon believed the thesis. But the stock traded at 40× earnings — "way too high for me." He never bought. With hindsight, 40× earnings in 1994 was cheap because it did not discount the extraordinary growth to come. The stock has risen roughly 100-fold since. The lesson cuts both ways: a great business at a seemingly expensive price can still be a bargain if the growth runway is long enough, but Ben Graham's margin of safety — articulated in 1949 — remains the cornerstone of intelligent investing. Judgment decides where the line falls.
Identifying Great Businesses Across Different Forms
Asked where beauty and value intersect today, Rochon points to CarMax: 15% annual EPS growth potential with margin expansion and buybacks, trading at 18× earnings — roughly the market multiple but with twice the growth profile. For managers he admires, he names Mark Leonard at Constellation Software: "he's an artist — really unique, really original, with a very, very long-term horizon on everything he does." There are many paths to wealth creation: Starbucks clones one concept globally, Berkshire grows through acquisitions, McDonald's franchise model scales. What ultimately matters over a decade is earnings per share growth. The principle applies regardless of the business model. For insurance-based compounders like Berkshire and Markel, price-to-book at 1.5–1.6× is a more appropriate valuation tool than P/E because earnings are more erratic.
Moats — How They Grow and Shrink
Moats are constantly changing — some expanding, some filling with sand. Rochon once asked Charlie Munger which company has an expanding moat; Munger replied "Google" without hesitation. That single comment prompted Rochon to take a fresh look at Google, and his firm bought shares in 2011 at 15× earnings. The stock has risen roughly 400% since. The key driver of whether a moat expands or shrinks is management — moats are not built by angels, they are built by human beings, and the culture set by top leadership determines their trajectory. But every investment situation is unique. An overly rigid analytical frame causes you to miss things. The right approach: have enduring principles and look for certain qualities, but judge every situation on its own parameters with an adaptive mind.
Four Reasons to Sell a Stock
Rochon outlines four reasons to sell. First: you realize you made a mistake — just sell, accept it as part of the process, and move on. Second: the nature of the business has changed — a new competitor, new technology, or deteriorating economics made it less great than when you bought it. Third: you disagree with a management decision, usually a large acquisition — investing is a partnership, and if you no longer trust management, there is no reason to remain a partner. Fourth and most common: you found a better opportunity — sell A to buy B, not because A has a problem, but because B offers superior prospects. Rochon emphasizes removing emotion from the selling process while accepting that as human beings, emotion is never entirely absent.
The Mistake Medals — Learning from Errors
Each year, Giverny Capital's annual letter awards bronze, silver, and gold medals to their most costly mistakes. Most are errors of omission — companies like Starbucks that fit every criterion but were not bought, sometimes for an overly simplistic reason, costing 10,000% gains over 25 years. Valeant was a commission error: Rochon had confidence in management but overlooked the excessive debt that violated their usual standards. They made money on the trade but still classify it as a mistake because the selection process was flawed. The distinction matters: it is only a mistake if the company was within your circle of competence and you failed to act, or you thought it was within your circle and it was not. Missing a 100-bagger you genuinely did not understand is not a mistake — it is staying within your boundaries.
How to Pay Up for Great Businesses
An audience member asks how to decide when to pay up for a great business, given that the best opportunities often appear when something seems wrong. Rochon explains his five-year forward earnings framework. When buying Disney in 2005, he projected $3 per share in earnings five years out, applied a 20× P/E to get a $60 target price, and bought at $30 — targeting 15% annual returns. Today's P/E ratio matters less than where earnings will be in five years. The same logic works in reverse: a stock that looks cheap today at 10× earnings but has no growth prospects five years out has no fundamental reason to be higher. Short-term multiple expansion might push it up in three months, but Giverny invests for at least five years, not three months.
Focus on Companies, Not the Market
Asked about current market risks and whether managers returning capital signals danger, Rochon acknowledges stocks are not as cheap as in 2009 — "but it was scary then too." He deliberately defocuses on what the market might do and focuses on the companies in his portfolio. His 25 holdings are expected to grow earnings 10–12% annually over the next five years at reasonable P/E ratios — "there's no reason to be worried." Looking at the broader market, he expects 5–7% annual EPS growth plus a roughly 2% dividend yield, translating to 7–9% total returns. That is not as exciting as buying at crisis lows, but it is still decent — especially compared to bonds yielding less than 2% over the same horizon.
Visa, MasterCard, Apple, and Google — Comparing Moats
An audience member asks why Rochon holds a tiny MasterCard position alongside a much larger Visa stake. Answer: both are fantastic businesses, but Visa has "a little something more." He holds a few MasterCard shares just to follow the company. Asked why he does not own Apple, Rochon admits it has been a great investment — up roughly 50× in a decade — and acknowledges the growing services revenue is strengthening the moat. But compared to Google, Apple's business relies more on selling new hit products every few years, which carries risk of missing a product cycle. Google's search business is more stable, entrenched, and recurring — so its moat is larger. That said, at 15× earnings for Apple versus roughly 25× for Google, the valuation gap is significant. For Visa at roughly 30×, Rochon cites Philip Fisher: "the further in the future you can see growth, the higher the P/E ratio you can pay."
Portfolio Overlaps and Cash-Adjusted Valuation
The audience member notes that through Berkshire Hathaway, Rochon already has indirect exposure to Apple. Rochon agrees but says that would not stop him from buying Apple directly if he found it attractive — indirect ownership through a holding company is not a reason to avoid a direct position. The host asks whether Rochon strips out excess cash when evaluating P/E ratios. Yes: cash that could be returned to shareholders should be backed out of the valuation. For Apple and Google, overseas cash trapped by tax considerations complicates this adjustment, but the principle stands. The proper valuation approach is to discount the sum of all future cash flows to today and then add the cash already sitting on the balance sheet.