Peter Lynch — Investing Principles (Investor Archive)
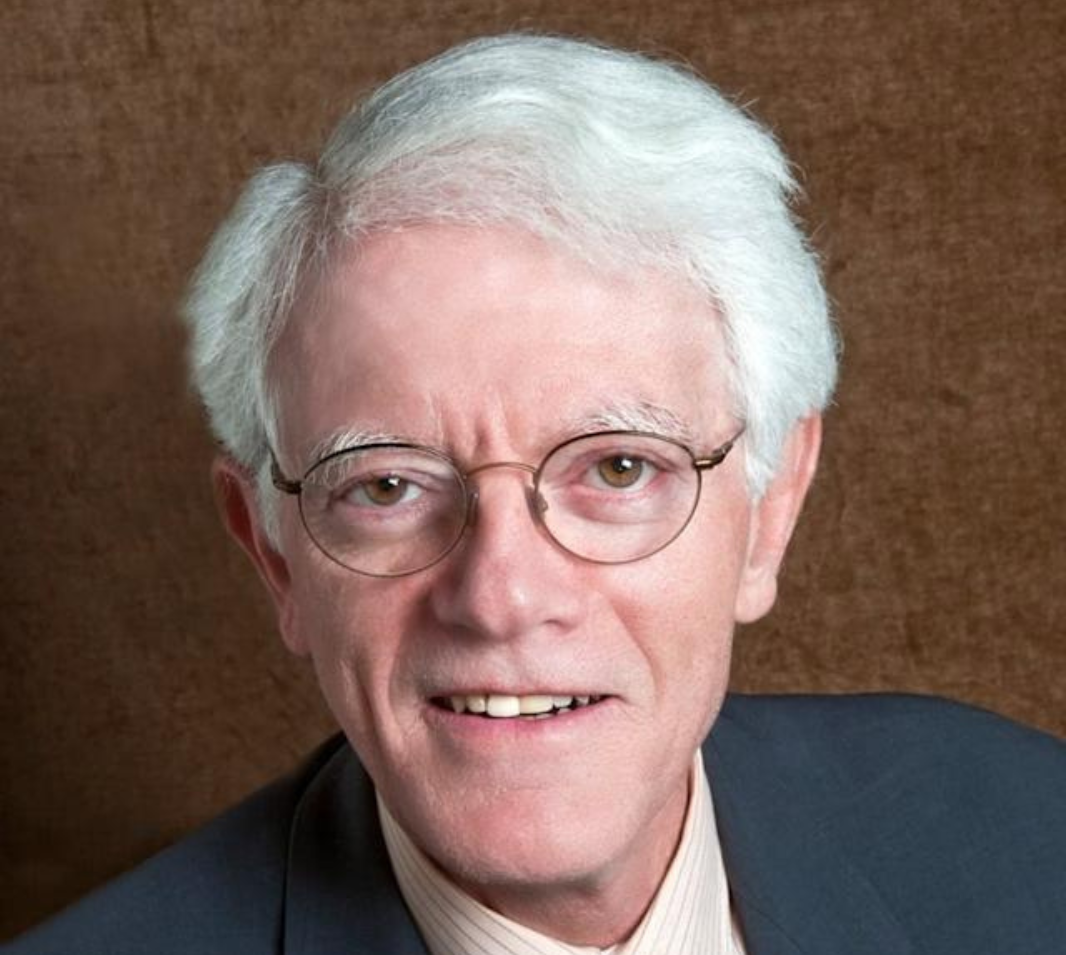
Peter Lynch delivers a lecture and Q&A on the core principles that guided his 13-year run managing Fidelity's Magellan Fund, during which it became the best-performing mutual fund in the world. He covers why you must know what you own, the futility of predicting the economy, and his famous "10 most dangerous things people say about stocks." The talk is packed with real trade examples, humor, and the kind of timeless, common-sense wisdom that made Lynch one of the most successful investors of all time.
Key Insights
- Know what you own
- You must be able to explain to an 11-year-old, in two minutes or less, why you own a stock. If you can’t, you won’t stay informed when things go wrong.
- Avoid long shots
- Sensational stories with no sales are no-shots, not long shots; he has never broken even on one. His 20–30x winners were boring businesses with real revenue.
- Buy the story
- Management is nearly impossible for an outsider to judge, so buy a story that works even if management leaves tomorrow — management is frosting on the cake.
- Don’t anchor on price
- A stock that has fallen can fall further, and one that has risen can keep rising. Price direction alone proves nothing — Polaroid went from 140 to 18.
- Ignore macro forecasts
- Predicting the economy, interest rates, and the market is futile — spend 13 minutes a year on economics and you’ve wasted 10. Deal in facts, not forecasts.
- Expect corrections
- In 96 years the market had 53 declines of 10%+ and 15 of 25%+. There is always something to worry about, and the market will be much higher in 15–25 years.
- Diversification & hunting ground
- Own 10 equally attractive stories and rotate capital as each improves or deteriorates, and turn over the most rocks — under-covered secondary stocks are the best hunting ground.
- When to sell
- Sell when the reason you bought the stock changes, not because the price moved — he sold Subaru at 320 when low-cost competitors arrived.
Know what you own
Lynch's first and most important rule: you must be able to explain why you own a stock to an 11-year-old in two minutes or less. Most people can't — they only know 'the sucker's going up.' He contrasts incomprehensible tech companies with simple businesses he made money on: Dunkin' Donuts, Stop & Shop, CVS, and Sallie Mae. If you don't know what the company does and why you own it, you can't stay informed when things go wrong.
Don't predict the economy; you have plenty of time
It's futile to predict the economy, interest rates, and the stock market. Lynch recalls the failed recession predictions from 1982 through 1990 — nobody called them correctly. His rule: if you spend 13 minutes a year on economics, you've wasted 10 minutes. Instead, deal with facts — inventories, copper prices, freight car loadings. And don't feel pressured: you could buy Walmart 10 years after its IPO, when it was only in 15% of the US, and still make 30 times your money.
"It can't go any lower" — the price-anchoring fallacy
Just because a stock has fallen doesn't mean it can't fall further. Polaroid went from 140 to 107 — people bought, then it fell to 18. Kaiser Industries went from 29 to 17 — Lynch bought a huge block, then it fell to 4. The corollary is equally dangerous: 'It can't go any higher.' Philip Morris went up 5x, people sold, then it became a 100-bagger. Home Depot and Toys R Us had the same pattern — investors sold too early because the stock 'had already gone up too much.'
It's always darkest before pitch black
Another dangerous idea: 'The business is terrible — you ought to buy the group.' Lynch uses freight car deliveries (96,000 → 45,000 → 25,000 → 7,000), oil rig counts (11,000 → 1,000), and the textile industry to show that terrible industries can stay terrible for decades. His expression for the textile industry: 'It's always darkest before pitch black.' A bad industry doesn't mean a turnaround is coming — it can get considerably worse, to 'terrible to the power of six.'
The stock doesn't know you own it
Lynch covers three dangerous mental traps: anchoring to your purchase price ('when it gets back to 10 I'll sell'), treating stocks personally like a grandchild or puppy, and the false comfort of 'conservative stocks.' Con Ed fell 80%, then tripled. Gulf States Utilities and Texas banks went to zero — 150-year-old companies are not automatically safe. The stock doesn't know who you are or what you paid — stop treating it like it does.
Missed gains, copycats, and price-direction bias
Three more dangerous mental habits: (1) Obsessing over stocks you didn't buy and treating missed gains as losses — 'you cannot lose money in a stock you don't own.' (2) Trying to catch 'the next one' — Toys R Us copycats like Child World and Lionel all failed. (3) Assuming a stock going up means you were right, so you double down — the average NYSE stock moves 50% from high to low each year, so a 10→13 move proves nothing.
Avoid long shots
Whisper stocks with sensational stories but no sales are 'no shots,' not long shots. These are companies that promise to cure everything — 'grow hair, make your kid have better spelling, your breasts can improve' — but have zero revenue. Lynch has tried 30 of these and never broken even on a single one. Meanwhile, he made 20–30x his money on boring businesses like Sallie Mae, MBIA, Fannie Mae, and Stop & Shop — stocks he never imagined would soar.
Management is hard to judge; stay flexible
Management is the single most important thing in a company, but it's nearly impossible for an outsider to judge great vs. good management in a one-hour meeting. You don't see the decisions they didn't make. Lynch's approach: buy the business story — assume management leaves tomorrow and the next generation takes over. If the story is solid, management is frosting on the cake. He also urges dropping all biases: great stocks exist everywhere — growth industries, non-growth industries, bankruptcies, new highs, new lows.
You only need fifth-grade math
You don't need a computer, calculus, or cosine to invest successfully. If you can add 8 and 8 and get fairly close to 16, you have all the math you need. The key questions are simple: how much debt, how much cash, how much are they losing per quarter? If you made it through fifth-grade math, you can handle stock analysis. Lynch illustrates with a football player who asked 'Does X always equal 7?' and never made it academically — the market doesn't need complex formulas.
There's always something to worry about
Every decade has its fears that kept people out of stocks. The 1950s: another Great Depression and nuclear war — yet it was one of the best decades for stocks this century. The 1970s: oil went from $4 to $40, experts predicted $100 — within two years it was at $14. The 1980s: LDC debt, money supply panic, Japan taking over the world. The market survived every crisis. There is never a clean, fear-free moment to invest.
Think like an eight-year-old
Younger people make better investors because they haven't heard about all the crises. An eight-year-old doesn't know about the money supply, the shape of the yield curve, or how many months into the economic recovery we are — and that's an advantage, because they expect great things from the next 20 years. Lynch shares his personal October 1987 crash story — golfing in Ireland when his $13B fund dropped to $9B in two days — then reveals the numbers: in 96 years, the market had 53 declines of 10%+ (one every two years) and 15 declines of 25%+ (one every six years). Corrections are normal. The market will be a lot higher in 15 and 25 years.
Q&A: When to sell, diversification, and where to look
Key answers from the Q&A: Sell a stock when the reason you bought it changes — Lynch sold Subaru at 320 when low-cost competitors arrived. International stocks are worth researching because there's less analyst coverage — 'the person who turns over the most rocks wins the game.' On diversification: he would own one stock if he could find one great one; instead, he buys 10 equally attractive stories and watches them unfold like poker hands, rotating capital as individual stories improve or deteriorate. Today's best hunting ground: secondary stocks among the 3,000 IPOs of the last four years, many of which are ignored after a stumble.