Charlie Munger — On Investing, China, Finance, and the Good Life
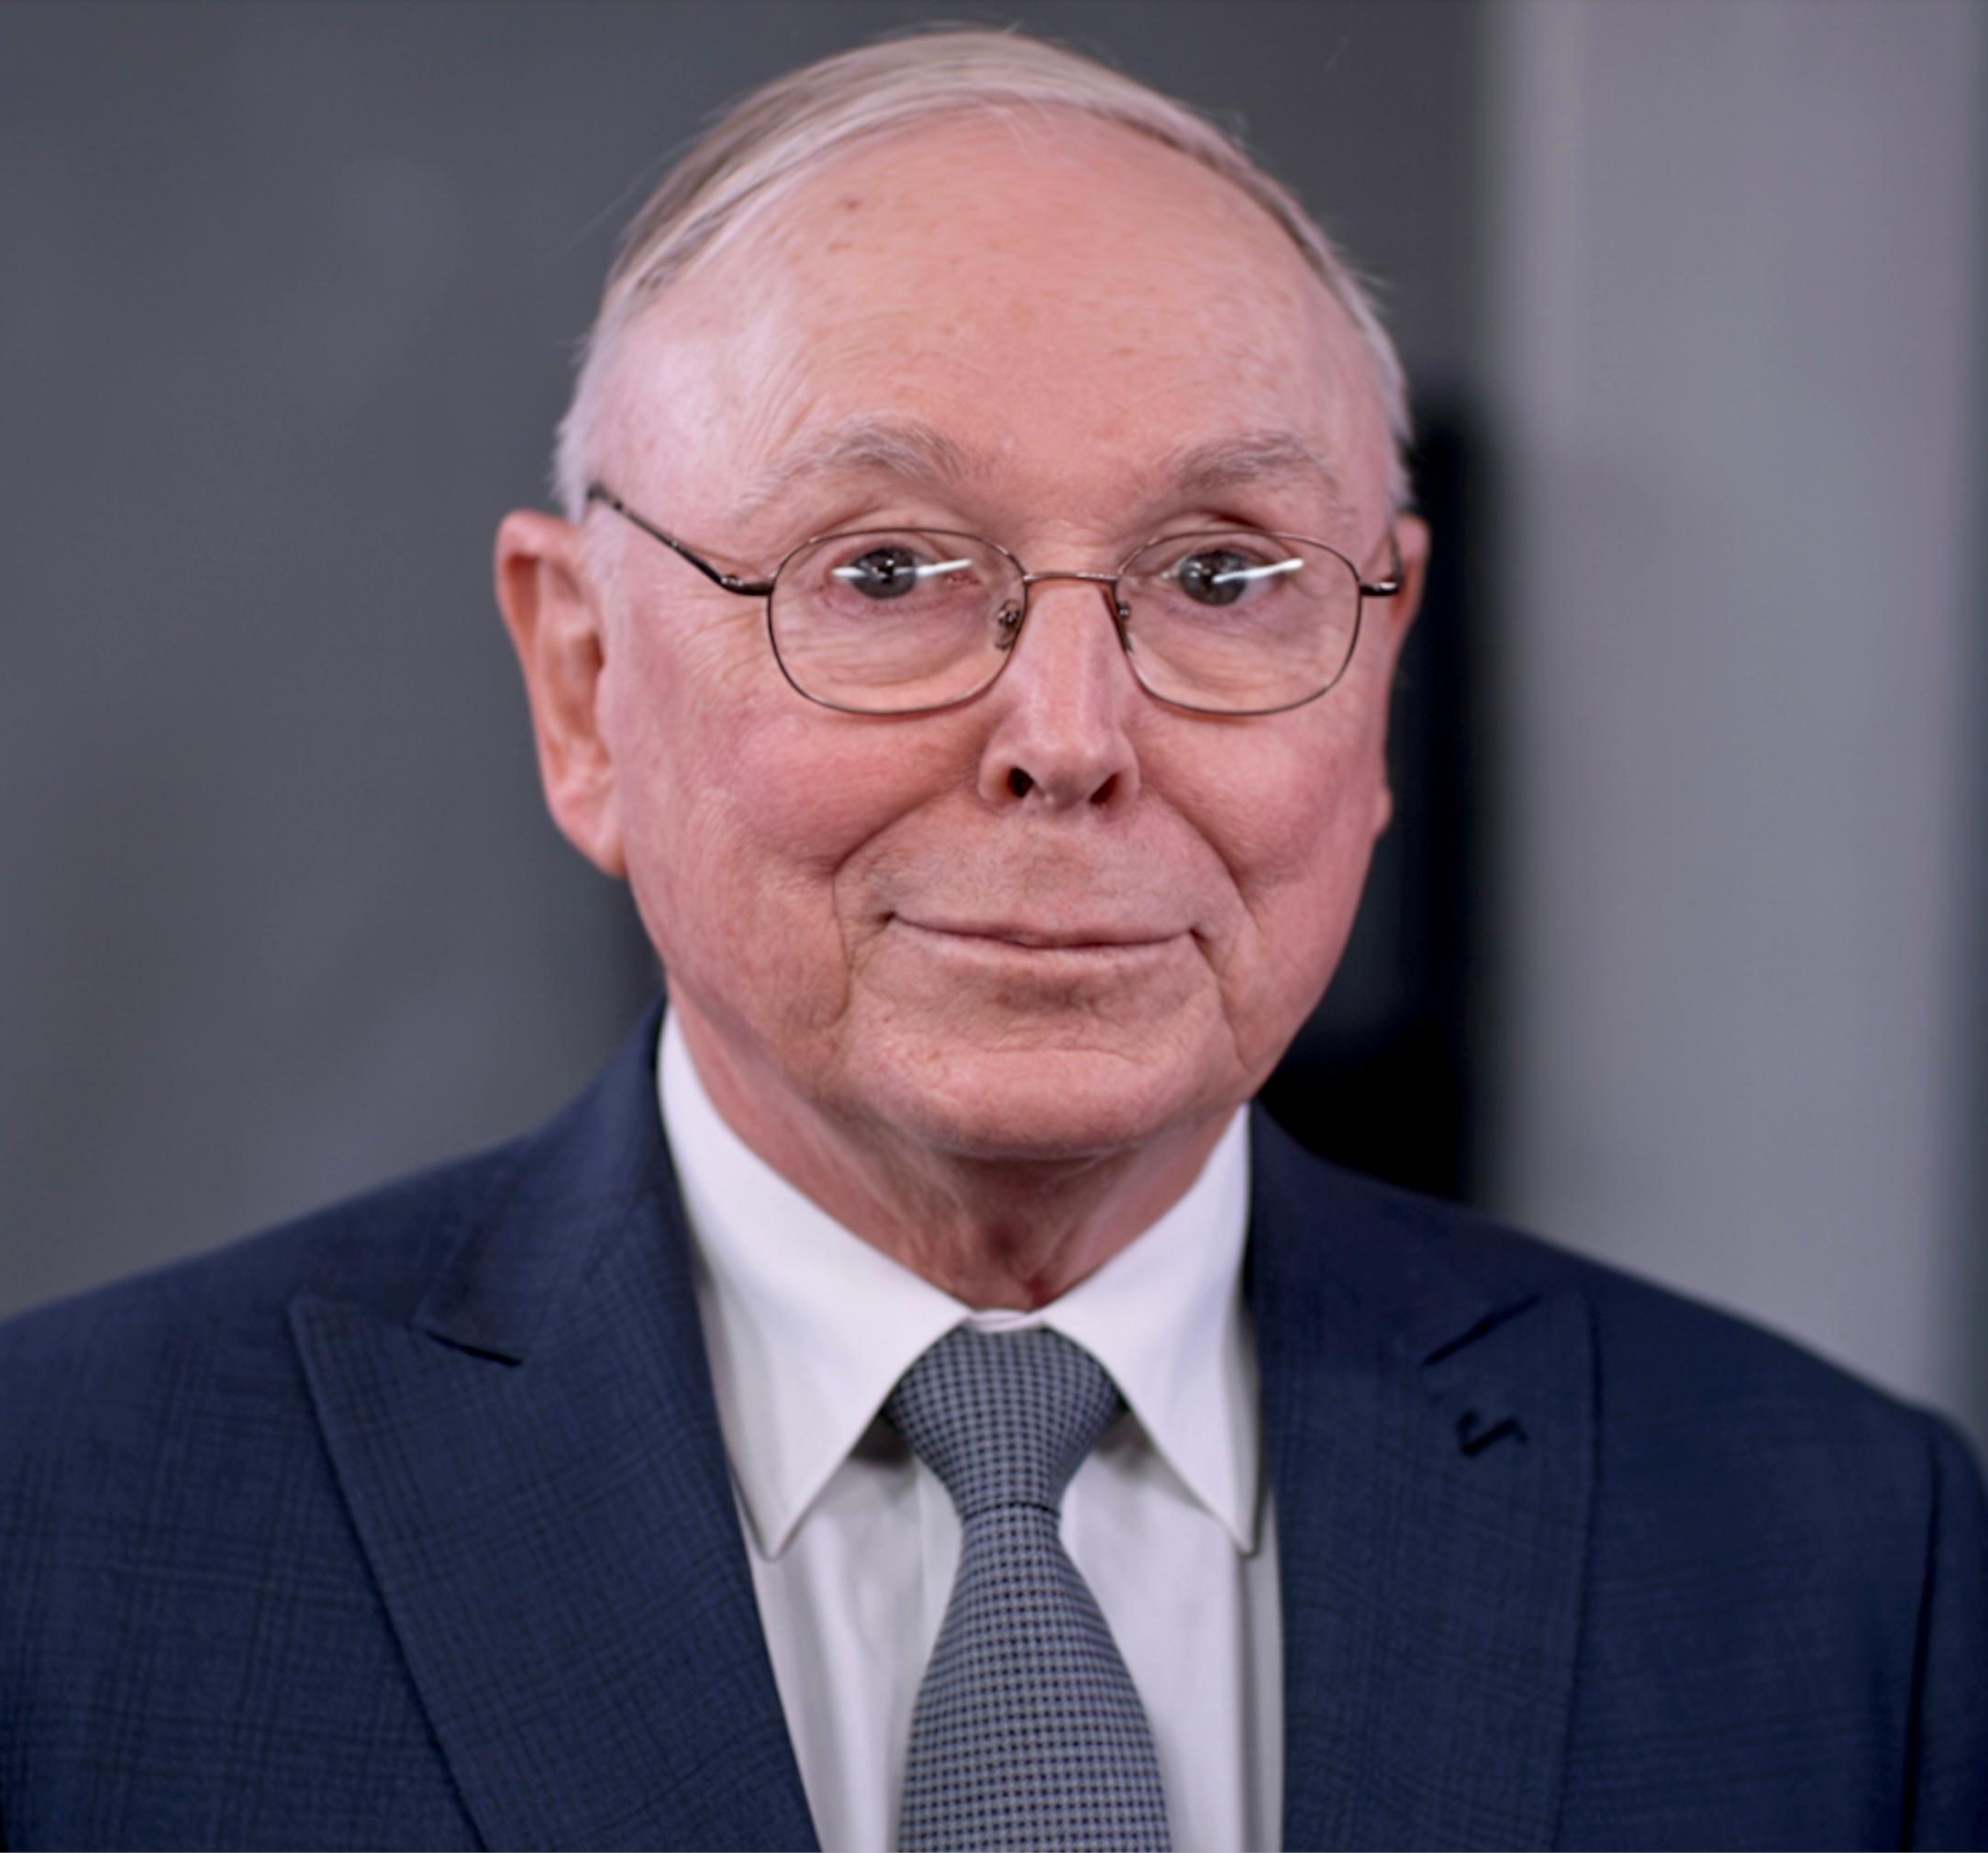
Interview by CNBC
CNBC is the leading global broadcaster of live business and financial news. Its long-form interviews with major investors, CEOs, and policymakers are among the most widely watched financial conversations in the world.
Recorded at the 2019 Daily Journal Annual Meeting, this CNBC interview captures Charlie Munger at his most candid — on whether the golden era of investing is truly over, why QE accidentally bailed out the rich, the structural case for US-China cooperation despite trade tensions, his disgust at pre-GFC banking behavior, why he distrusts economists, and the deceptively simple rules he believes make for a long and happy life.
Is the golden era of investing over? Harder now — but not forever
Munger opens by saying the golden era of investing is not gone permanently, but it is genuinely harder now: valuations have risen and competition has become more intelligent, more aggressive, and more numerous. The fabulous track records of his generation were built on a rare post-war window when roughly 90% of natural stock buyers grew so discouraged that equities were left deeply undervalued — a generational opportunity that rarely repeats. He acknowledges 2008 may have been another such generational low, and notes that the Daily Journal's well-timed bank stock purchases around that period were partly accidental. He then turns to QE: the central bank interventions were necessary — without them, the world risked a revisitation of the conditions that brought Hitler to power — but they had the ironic accidental effect of bailing out the asset-rich while supposedly helping the poor.
Political fixes for inequality, the national debt, and why two-party balance works
Munger is skeptical of popular proposals to address inequality — 70% tax brackets, wealth taxes, banning buybacks — arguing the QE-driven inequality spike was a fluke that cannot easily recur. He prefers the current mixed system: two parties alternating control, a social safety net that is necessary but not extravagant. His principle is that the country has run best when neither party held total power. On the national debt at $22 trillion: uncharted territory, but great nations all decline eventually and he is not panicking about the timing. On politicians worth admiring: Bloomberg ran New York reasonably well; otherwise the political class is not his favorite genre, and he would rather stay cheerful than rage at things he cannot change.
China, trade, and why Munger stays bullish on cooperation
Munger says some trade tension with China is natural: Ricardo's law of comparative advantage did not foresee that free trade would allow a uniquely able nation to rise as rapidly as China has, disrupting industries built on the old order. Some limits on free trade are acceptable — particularly in strategic sectors like aerospace. But his deeper conviction is structural: both countries have too much to lose from genuine conflict. Munger states plainly that he prefers the US relationship with China to its relationship with Russia, and anticipates that rational self-interest will drive continued cooperation despite the tensions.
Nuclear war: the defining unsolved problem of Munger's lifetime
Asked what worries him most, Munger answers without hesitation: nuclear war. He has worried about it every single day since the hydrogen bomb was invented, calling it mankind's defining unsolved problem. He ranks it far above AI or climate change — global warming is something humanity can adapt to, but a nuclear exchange would be an unrecoverable disaster. He points to the deteriorating US-Russia relationship as a cautionary example of what the US-China relationship must avoid, and notes that this concern has shaped his worldview for decades.
Amazon, Bezos, and why driving out the rich is dumb policy
When Amazon withdrew its HQ2 bid from New York, Munger calls Amazon a phenomenon of nature — something he would not have predicted and would not predict stopping. He admires Bezos for confronting the National Enquirer blackmail head-on, viewing directness in the face of problems as an admirable trait. On the broader policy question: states that attract wealthy residents — Florida, Hawaii — have been smarter than those driving them out. Connecticut has seen high-end real estate fall 50%; California is making the same mistake. Munger's logic is simple: rich residents keep hospitals busy, do not burden schools or prisons, and pay enormous taxes. Driving them out punishes the state's own finances for ideological satisfaction.
Bad behavior in finance, the GFC, and staying far from the whirlpool
Munger calls the behavior of the mortgage and banking industry in the lead-up to the financial crisis obscene — lying, cheating, and delusional assumptions that he compares to adulterating baby food. He believes the perpetrators deserved harsher consequences and agrees with Elizabeth Warren on this point, despite disagreeing with her on almost everything else. On the ongoing monetary risk: both parties prefer to believe money printing has no consequences, but Munger points to the Roman Empire and Weimar Republic as warnings. His personal rule for navigating truly dangerous things is not to see how close you can come without being consumed — but to stay a long way away. He would rather rubberneck at the whirlpool from a distance than try to run the rapids.
What surprised Munger: central banks printing money to buy private assets
Asked what recently caught him off guard, Munger points to central banks: he was surprised when they started printing money and buying massive amounts of private securities. QE worked — so far — but Munger is characteristically cautious: all human successes are successes so far. Whether Japan can simply keep doubling its national debt, he genuinely does not know, and he distrusts anyone who claims to. The deeper concern is structural: money printing is politically convenient, so both parties have an incentive to believe it has no consequences. Munger's response is to stay far away from things he considers big and dangerous.
Why economists are always wrong — and the secret to a long happy life
Munger explains why he distrusts economists: economics is not like physics. The same policy recipe applied in a different era gets a different result. You cannot step in the same river twice — the man is different and so is the river. He closes with his formula for a long and happy life, which he calls almost embarrassingly simple: no resentment, don't overspend your income, stay cheerful despite your troubles, deal only with reliable people, and do what you are supposed to do. He says he had this figured out by age seven, having noticed irrationality in the adults around him from an early age. On children and parenting: they arrive largely pre-made, and he has found no way to alter what was built in at birth.