Charlie Munger — Investing Wisdom & Life Lessons (Yahoo Finance)
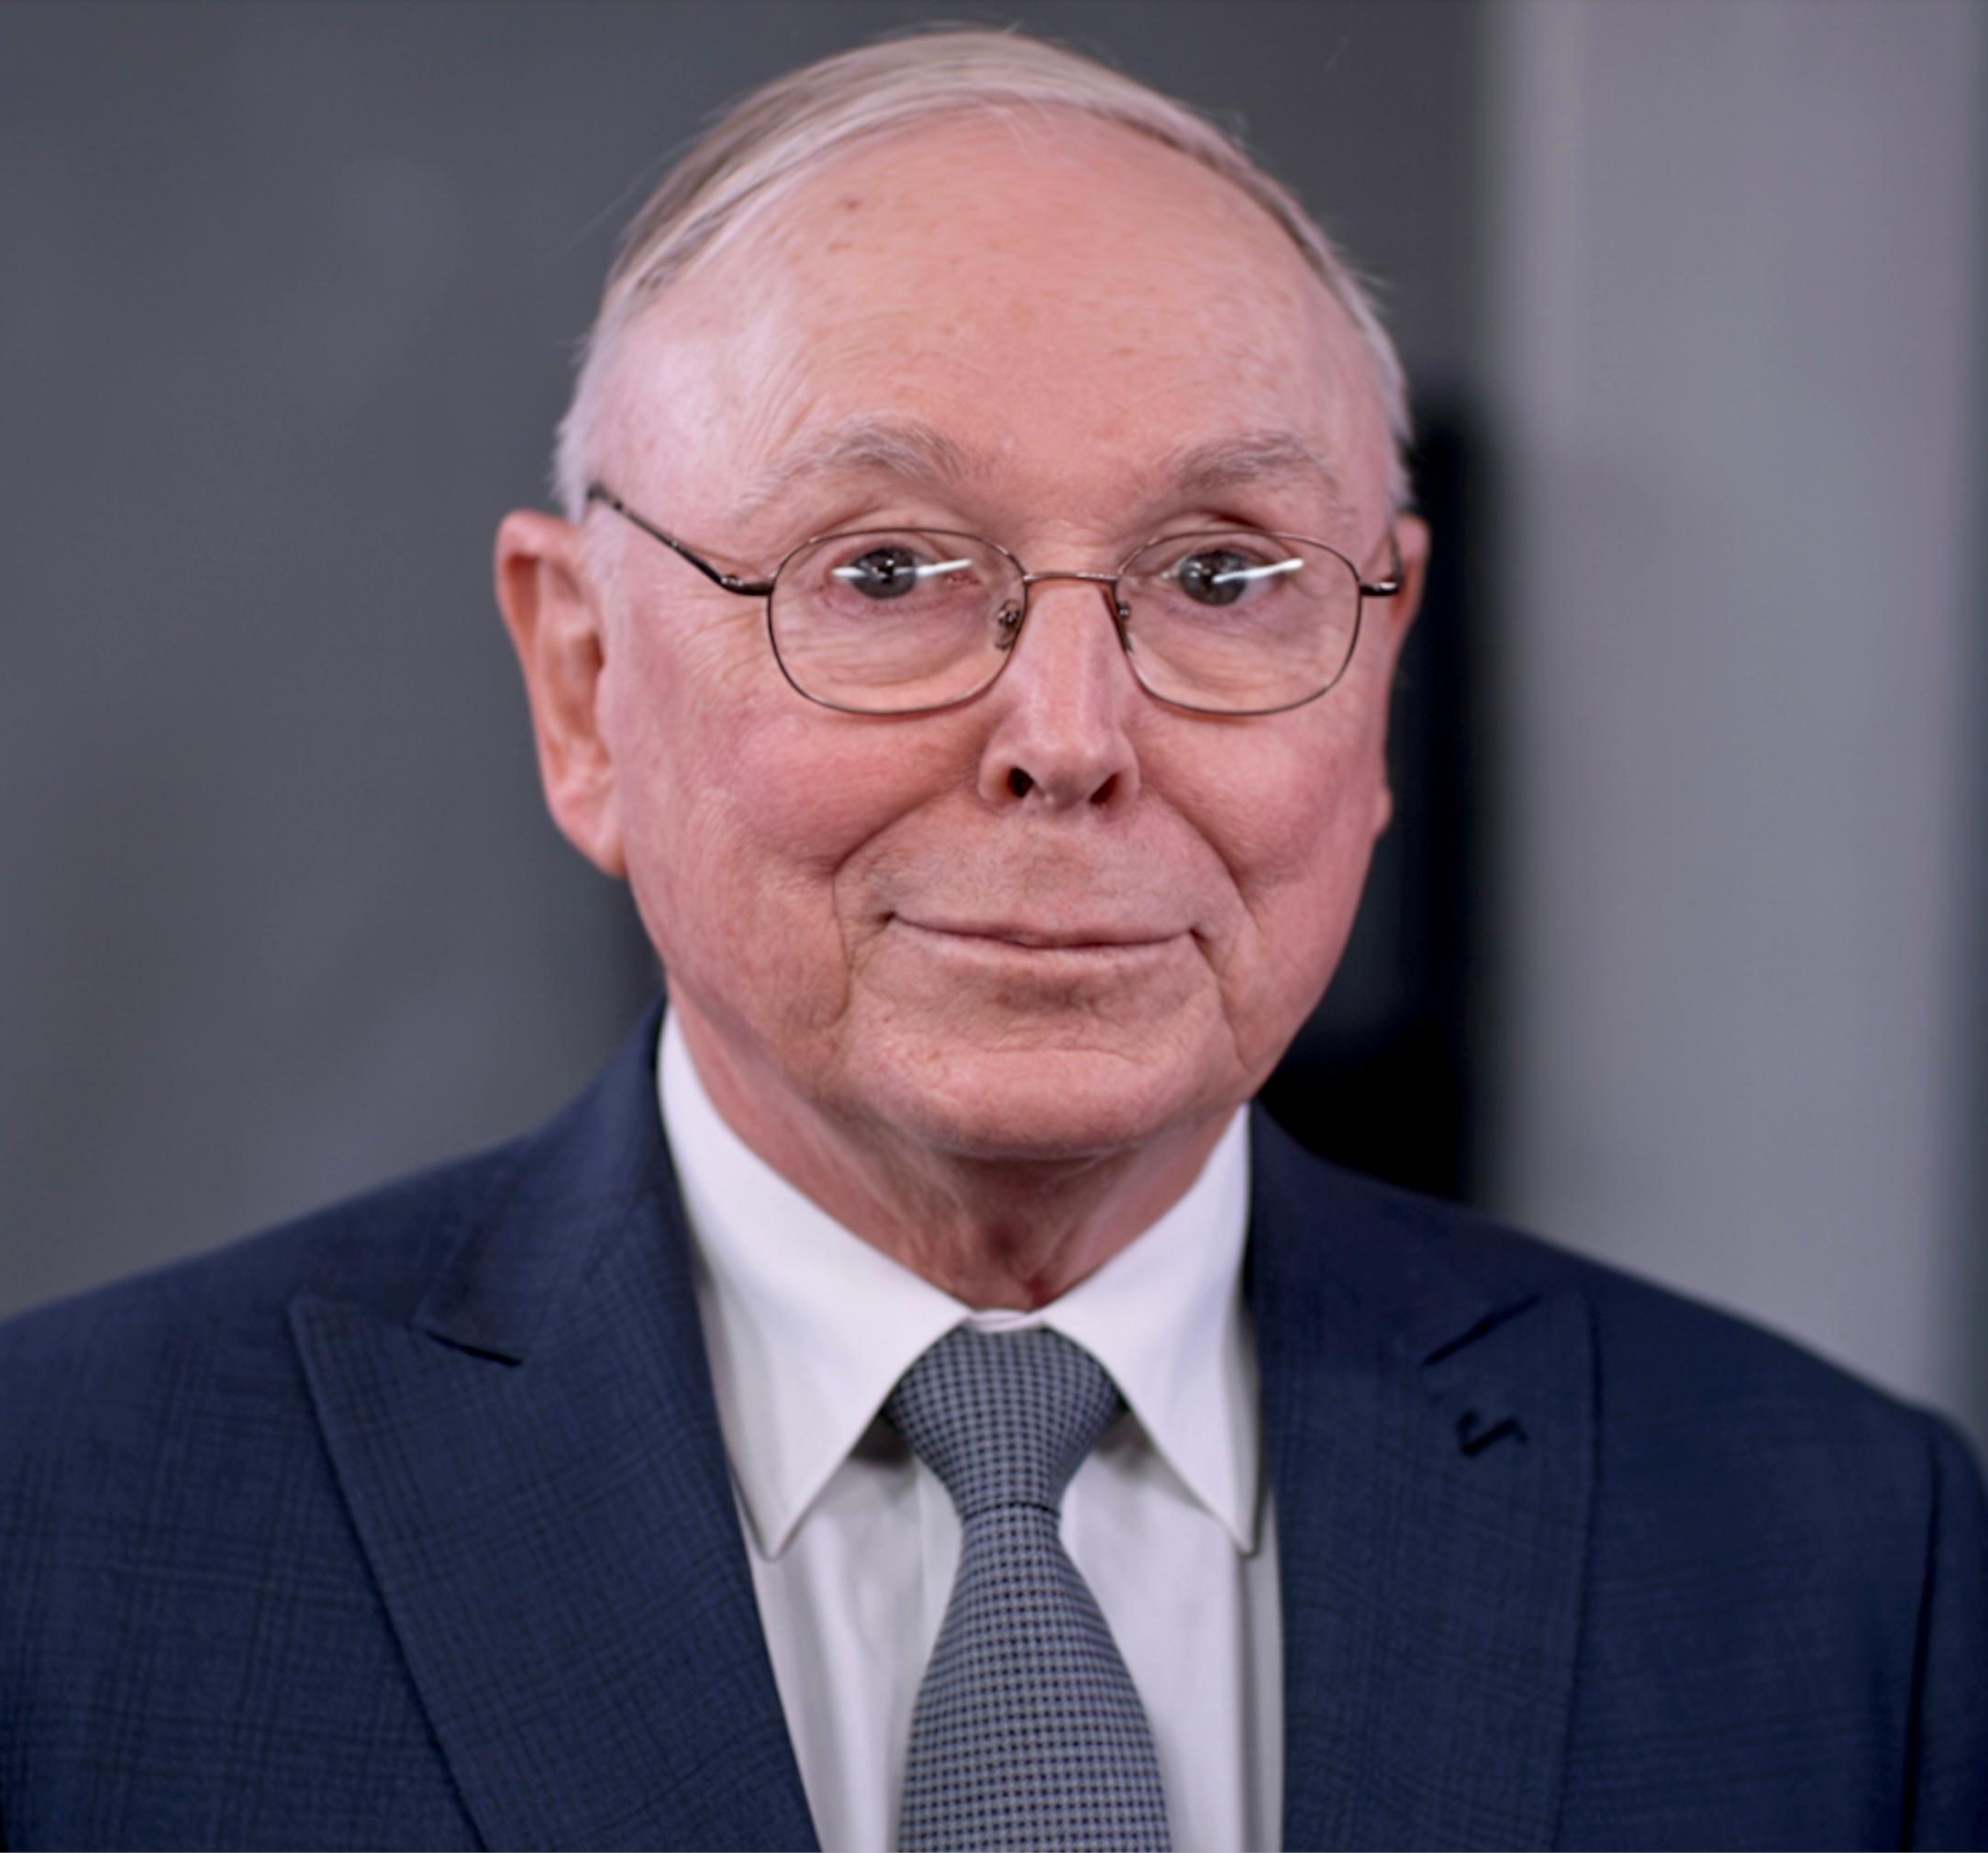
Interview by Yahoo Finance
Yahoo Finance is one of the most visited financial news platforms in the world, offering market data, analysis, and original video content including interviews with prominent investors, fund managers, and market strategists.
In a wide-ranging conversation with Yahoo Finance Editor-in-Chief Andy Serwer, the 95-year-old Munger shares the mental models that built Berkshire Hathaway: why common sense is uncommon, how he shifted Buffett from cigar butts to great businesses, and the non-bureaucratic culture that lets Berkshire do billion-dollar deals overnight. He also weighs in on China’s economic miracle, the money-printing experiment, and why avoiding partisan anger is an investing virtue.
The uncommon sense of investing
Munger explains why “common sense” is a misnomer — what people mean is uncommon sense, because the standard human condition is ignorance and stupidity. Investors and ordinary people alike do not think clearly about money, sex, or gambling because of widespread “miscognition.” The path to improvement is twofold: eliminate your own miscognitions, and recognise them in others. The Berkshire annual meeting works because shareholders feel they are on the right side of something — Munger calls it a “good cult.”
Terra incognita: the great money-printing experiment
Munger describes the post-2008 era as “total terra incognita in economics” — never before had so much money been printed and spent so fast, with so much public and private debt bought back. No one knew for sure how it would work. It was risky but necessary: Congress had no other tools because democratic inertia blocked conventional fiscal stimulus. Both parties cooperated — Munger notes wryly it was “the last time.” His philosophy through it all: “We just keep swimming — sometimes the tide is with us, sometimes against, but we keep swimming either way.”
The Tooth Fairy of debt — and why Singapore gets it right
Presidents have always lobbied the Fed to keep rates low — “of course it’s not a good idea.” The best example in the world is Singapore: zero national debt, never prints money and spends it, and it is one of the most successful places on earth. On those who claim US federal debt is not a problem: “If you believe that, you believe in the Tooth Fairy — because then we don’t have to have any taxes ever, we’ll just print money and live happily ever after.” But the truly hard question is knowing when printing becomes counterproductive — and Munger admits nobody really knows where that point is. On Jay Powell: “as good a choice as we could have made.”
Inequality was an accident — and the blindness of partisan anger
Wealth inequality, Munger argues, was an accidental byproduct of a correct governmental decision — printing money and driving rates to zero lifted asset values for those already rich, but nobody intended it. “It will go away by itself — there’s no reason for a lot of screaming.” On progressive proposals: he likes Elizabeth Warren’s manner but not her attitude — “I don’t think she’s studied Adam Smith enough.” As for AOC, “I don’t think she knows who Adam Smith was.” More broadly, he refuses to be consumed by political anger: “Both parties are so partisan now they’re blinded by their anger.” Anger feeds on itself — he controls it and recommends the same to both parties. He misses the Eisenhower-Stevenson era’s civility.
How Munger shifted Buffett from cigar butts to great businesses
Munger describes his most consequential contribution to Berkshire: persuading Buffett to move beyond Graham-style cigar butt investing. “It was perfectly obvious — he made so much money in the other technique it was hard for him to leave something that worked so well, but it was not going to scale.” The shift: start looking for investment values in great businesses that were temporarily under pressure. “It changed everything for the better — now we could scale up to the big time.” Asked what brand Buffett would buy if he could only own one forty years ago: Gillette. Today? Still Coca-Cola — “one hell of a brand,” and one where Munger’s judgment is far better than on internet companies.
Kraft Heinz, Wells Fargo, and Boeing: three case studies in business judgment
Three quick case studies in business judgment. Kraft Heinz: Heinz ketchup was the stronger brand and Kraft cheese the weaker — one acquisition worked brilliantly, the other poorly. “Welcome to adult life — it happens to everybody.” Wells Fargo: Tim Sloan should still be CEO — he was not responsible for the crazy incentive system that created the fake-accounts scandal. He was thrown out “the way you take out the charwoman when you’re really gambling.” Boeing 737 MAX: Boeing has probably the best 60-year safety record in the world — this was a very unusual lapse, not a symptom of software becoming too powerful. They will fix it, and there may not be another one for 60 years.
Billion-dollar deals overnight: Berkshire’s non-bureaucratic advantage
Munger cannot recall a single example in his entire life where Berkshire’s practice of doing billion-dollar deals on short contracts ever blew up on them. “Keeping it simple — what has worked against us? We’ve made mistakes, but they weren’t because we kept it simple.” The chief advantage Berkshire has had in accumulating a good record is avoiding pompous bureaucratic systems and giving power to very talented people to make very quick decisions. On succession: the next generation are steeped in these non-bureaucratic ways, and it is amazing how good they are. “Getting it done is when it’s done, not when it’s in somebody else’s inbox.”
China’s remarkable rise — and the Lee Kuan Yew connection
No nation that big has ever advanced as fast as China did — and it did so using the savings of poor people (a 50% savings rate), not the wealth of the rich world. The secret: China copied Singapore’s Lee Kuan Yew. “The Communist leader said I don’t care if the cat is black or white as long as it catches mice.” Munger is a huge admirer of what the Chinese have accomplished and remains quite optimistic — “they’re getting ahead, they’re not moving backward.” On US-China relations: “If both sides have any sense, they will be better and better friends and adjust all differences — it’s just raving madness on either side not to make a friend of the other really powerful nation on earth.”
The Google miss — and the art of predicting the predictable
Munger says he is ashamed of missing Google — Berkshire could see from its own operating companies that Google’s advertising was working way better than other advertising. “We just weren’t paying enough attention.” He has never owned Amazon despite being a huge admirer of Bezos — “it’s always been too complicated and uncertain for my particular temperament.” On the flood of unprofitable tech IPOs: “It’s not my scene. I’m looking for things where I think I can predict what’s going to happen with a high degree of accuracy — and I have no feeling that I can do that with Uber.” The meta-lesson: Munger’s edge is not in analysing every opportunity, but in knowing which ones sit within his circle of competence.
Share repurchases: simple morality
Munger defends share buybacks with characteristic bluntness: “If you had a partnership of three of your crippled relatives and one needed some money, wouldn’t you buy out the broke one with the company’s money? It’s just simple morality.” But he draws a sharp line: Berkshire will only buy back shares when they are too cheap — never to prop up values at inflated prices, which he calls “an improper use of the technique.” Some companies have overdone it, repurchasing even when prices were too high. Should there be laws? No — “we shouldn’t be telling people what the right price is.”
The Mozart story: career advice for the young
Young people often ask Munger how to become a billionaire. His response is the Mozart story: a 22-year-old tells Mozart he wants to compose symphonies. Mozart says he is too young. The young man protests: “But you were composing at 10 years old.” Mozart replies: “Yes, but I wasn’t running around asking other people how to do it.” Munger’s own philosophy — being very rational and disciplined — will work for anyone, but “floating around” between careers trying to outdo others in their own territory will not work for most people. He credits luck as well as skill: “The combination of luck and skill — that’s what all good records are.” His Army experience reinforced his hatred of bureaucracy and his preference for controlling his own destiny.
The unscripted genius of Berkshire
Munger reveals that he and Buffett say absolutely nothing to each other before sitting down at the annual meeting. “You have no idea what’s gonna happen — that is correct.” The spontaneity is deliberate: if they scripted things, people would not like it. He cannot sign the Giving Pledge because he already transferred more than half his wealth to his children — his late wife would have preferred it that way. On the future of Berkshire: “What worked in one era doesn’t have to be duplicated. I think it was a historical accident — we didn’t do it on purpose, we drifted into it, and when it worked we fanned the flames.” Some later generation will have a different system. “There’s more wise-assery in our meeting than would be appropriate forever — no, I’m the principal wiseass.”