A Conversation With Stanley Druckenmiller (Bloomberg)
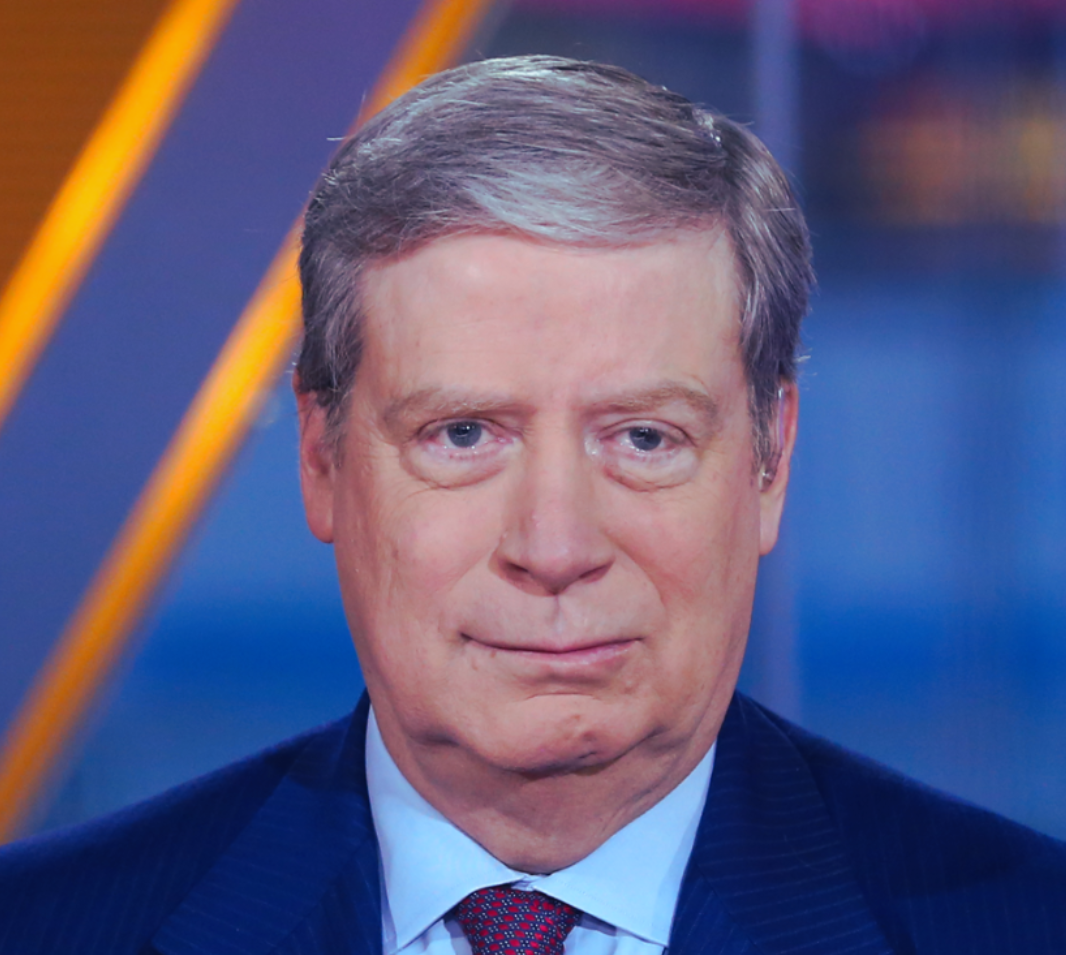
Interview by Erik Schatzker
Bloomberg Television is the global business and financial news network. Its interviews with the world's most influential investors and business leaders set the agenda for markets worldwide.
Druckenmiller sits down with Bloomberg's Erik Schatzker to discuss his constructive 2020 market outlook driven by unprecedented global fiscal and monetary stimulus, his portfolio rotation from cloud growth stocks to cyclicals and commodity currencies, the investment case for post-Brexit Britain, why he's become 'a coward' in managing his own money, a sharp critique of the Fed's rate policy and Jay Powell's leadership, the three triggers he sees for the next bear market, and a data-driven defense of capitalism against attacks from both political extremes.
Market Outlook: All Systems Go
Erik Schatzker opens by asking how Druckenmiller feels going into 2020. Druckenmiller is unequivocally constructive: low unemployment in the US, fiscal stimulus in Japan and Britain, green stimulus coming in Europe, and negative real rates everywhere. Expansions don't die of old age — they end with tight monetary policy or credit problems, and neither is present. The intermediate-term technicals are good, breadth is at all-time highs, the economy is fine, and the global trade war is de-escalating rather than escalating. For now, all systems go.
Inside the Portfolio: Copper, Currencies & Cyclicals
Schatzker asks for specifics on how Druckenmiller is expressing his constructive view. He's long equities, long copper, long commodity currencies (Canadian, Australian, New Zealand dollars, and Mexican peso), and short the long end of the bond market — all bets on a benign economic outlook. Copper gets a special kicker from EV-driven demand growth of 0.5% per year with challenged supply. On the equity side, his portfolio has rotated dramatically from cloud growth stocks (ServiceNow, Microsoft) to companies that benefit from higher nominal growth — banks, financials, and Japanese equities. He's no longer concentrated in low-growth-world winners.
The UK Bet: Why Britain Is a Bargain
Schatzker pivots to Druckenmiller's favorite currency: the British pound. Druckenmiller was long sterling heading into the 2019 UK election, believing the British people would reject socialism — his friend referred to Margaret Thatcher as proof that British common sense prevails. He breaks from consensus on Brexit, calling it positive for Britain: the country thrived for 500 years without the European Union. Boris Johnson is 'a smarter version of Trump without the antics.' The UK offers 12x earnings with a 4% yield, lower debt-to-GDP than the US, and a 2% deficit — a far more attractive package than the US on paper. He also owns British financials — Barclays and Lloyds.
Why I've Become a Coward
Druckenmiller admits he's become 'a coward' since he stopped managing outside capital. In 2019 — an extraordinary year for investors — he only made low double digits. He was well-positioned but executed timidly. The reasons: managing his own money feels different than competing with other people's capital; the competitive compulsion to take risk has faded; and perhaps most importantly, the Trump administration's unpredictability — 'wondering where the hell the next bomb is coming from' — makes it impossible to size positions with the conviction he historically deployed. He calls the phenomenon 'policy uncertainty,' and says it's kept him from taking the kind of one-way bets that defined his career.
The Fed's Dangerous Easing
Druckenmiller launches into a sharp critique of Fed policy. Jerome Powell won't have the courage to raise rates in 2020, but rates at 1.5% are absurd given full employment and nominal growth — he'd guess the appropriate rate is 3.5%. He's expressing this view by shorting the long end of the Treasury curve. The pattern repeats: Bernanke declared victory with the Great Moderation in 2004, Greenspan was called the Maestro — then the financial crisis happened because of bubbles created by easy money. Negative rates, which Trump has been pushing, are 'the most anti-capitalist idea I could ever dream up.' He grades Powell as a weaker version of Yellen — lacking Bernanke's conviction and ability to control the room. His true hero remains Paul Volcker, who had real courage.
Wrong Call, Right Pivot
Schatzker holds Druckenmiller accountable for his prediction a year earlier that markets were in a global bear market, not just a correction. Druckenmiller admits he was 'absolutely wrong' — stocks are at new highs twelve months later. But he's proud he pivoted before it was too late. He notes the US was the only market that continued rallying until recently. The key question now: how long can this last? Nobody knows — maybe Jim Simons' machine knows, but mere mortals don't. Predicting turnarounds is awfully hard, even for someone who's made more money in bear markets than bull markets.
Three Triggers for the Next Bear Market
Schatzker asks what will trigger the next downturn. Druckenmiller identifies three scenarios. First, political: if an anti-capitalist wins the White House, that would definitely trigger a bear market — the question is whether it permanently ends the bull market. Second, monetary: if inflation picks up enough by year-end that the Fed is forced to tighten. Third, a credit event: with interest costs so low, there are 'a lot of bad apples out there that are not being exposed' — including the US government itself, running a trillion-dollar deficit simply because it can. The new academic consensus that deficits are a free lunch is, in his view, dangerously naive.
The Capitalist's Defense
Schatzker asks whether an Elizabeth Warren presidency would really be that bad. Druckenmiller says it would be great for his business — his fund has a negative correlation to the S&P 500 and thrives in bear markets — but not good for America. He then delivers a data-driven defense of capitalism. Poverty in the US has fallen from 26% decades ago to 13% today — an all-time low. After accounting for government transfers, the bottom quintile has seen the same percentage income gains as the top quintile. The anti-capitalist narrative doesn't match the facts. Both parties are undermining markets: Trump's tariff regime is effectively a Politburo picking winners and losers, while negative rates globally have destroyed the hurdle rate that lets markets allocate capital properly. Taking from billionaires doesn't give to the poor — 'that's not the way it works. It's not a zero-sum game.'